How to Compare Health Insurance Plans
When it’s time to buy health insurance and compare health plans, it’s easy to default to the one with the lowest monthly payment. However, looking at the monthly premium alone only tells part of the story. To truly understand what your health coverage will cost, you have to look at the total financial picture, including out-of-pocket expenses like deductibles and coinsurance. And don’t forget to check the fine print for coverage limitations, network restrictions, and exclusions.
This article is part of Decoding Health Care’s Health Insurance Literacy Series. Before you compare health insurance plans, you may find it helpful to review the basic vocabulary of health insurance terms related to costs and coverage.
Table of Contents
- No One-Size-Fits-All: The Cheapest Premium May or May Not Be the Best Deal
- How to Do Health Insurance Math Without a Crystal Ball
- How to Compare Health Insurance Plan Costs Like a Pro in 3 Steps
- Free Help Comparing Medicare and Marketplace Plans
- Online Tools for Comparing Health Insurance Plans
- Comparing Health Insurance Plans: Restrictions and Denial Rates
- Confusing Health Insurance Plan Marketing and Scams
- Conclusion
- Frequently Asked Questions
No One-Size-Fits-All: The Cheapest Premium May or May Not Be the Best Deal
Choosing a health insurance plan with the lowest premium and potentially saving hundreds of dollars a month looks like a clear win for your budget. However, lower premiums almost always come paired with higher deductibles and out-of-pocket costs. It can also mean coverage gaps, leading to surprise bills for services you thought were covered.
Expected Medical Needs and Cash Flow
When you compare health insurance plans to determine which is truly more economical overall, you have to look at additional factors like your expected medical needs for the year ahead and your cash flow.
The Chronic Condition Gray Area
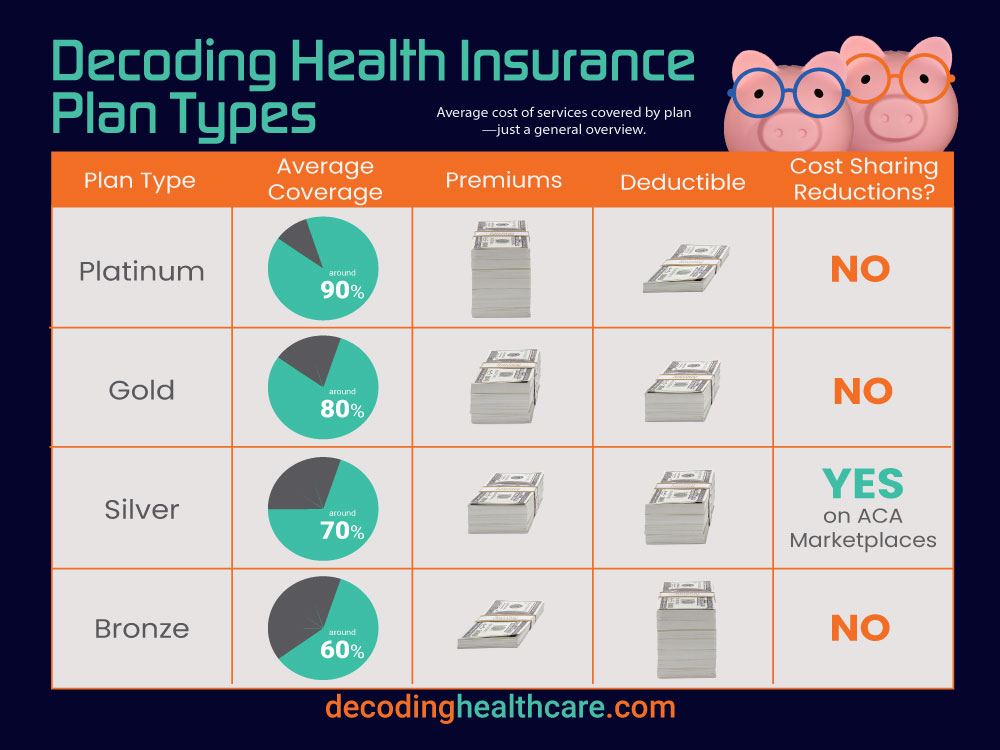
Conventional advice often says that if you have a chronic condition, you should automatically buy a low-deductible plan like a Gold or Platinum-level health plan. But that isn’t always true. If a Gold plan costs, for example, $500 more per month than a Bronze plan, you’re paying an extra $6,000 a year in extra guaranteed premiums (before any subsidies) in trade for that lower deductible. If your routine care and medications cost less than that difference, a high-deductible plan might still come out ahead financially—provided you have the income/savings to handle frequent medical bills as they happen.
The Cash Flow Reality
Of course, health insurance math is heavily tied to your bank account. If you don’t have cash on hand or emergency savings, a high-deductible plan can be risky because a single unexpected medical bill can force you into medical debt if you can’t pay the deductible amount, even if the annual math looked cheaper on paper. Conversely, if you have some savings and predictable, moderate health needs, pocketing the monthly premium savings often works out in your favor. (And remember you can use your Health Savings Account or Flexible Spending Account, if you have one, to pay ongoing health costs.)
How To Do Health Insurance Math Without a Crystal Ball
When you compare health insurance plans, it’s nearly impossible to predict your exact medical bills for the year. Instead of trying to guess every single doctor visit or prescription cost, financial planners and insurance experts recommend looking at health insurance as a range defined by two clear numbers: your guaranteed minimum and your absolute maximum.
Your Best-Case Cost (the Minimum)
If you stay completely healthy all year and only use free preventive care (like your annual physical and/or vaccines), you will pay zero out-of-pocket for covered medical costs. Your total health insurance cost for the year is simply your annual premiums (monthly premium x 12).
Your Worst-Case Cost (the Maximum)
If you face a major medical event, many doctor visits, or expensive procedures/medications, you will pay your share of all of these costs until you reach your health plan’s Out-of-Pocket Maximum.
Your financial ceiling for covered health-related expenses for the year is:
Out-of-Pocket Maximum + Annual Premiums
= Maximum Possible Annual Health Insurance Cost
When you compare health insurance plans, such as a lower-premium plan and a higher-premium plan (like a Bronze vs. Gold plan on the Marketplace), compare their worst-case maximums side by side. While a health insurance plan with a higher monthly premium will have a lower deductible and lower out-of-pocket maximum, you have to factor in what you are guaranteed to pay in monthly premiums all year plus the extra you might have to pay for services to see which plan actually offers the lowest total ceiling if the worst happens.
How to Compare Health Insurance Plan Costs Like a Pro in 3 Steps
When you are ready to compare health insurance plans and evaluate your options, following a structured approach can remove the guesswork.
Step 1: Audit Your Expected Healthcare Needs
Look back at the previous year and anticipate the next. Do you have routine check-ups, multiple ongoing prescriptions, planned procedures, or family medical needs? Listing these out helps you gauge whether you are likely to exceed your deductible or not.
Step 2: Check the Provider Network and Prescription Formulary
A health insurance plan is only useful if your doctors and local hospitals accept it and your medications are covered. Start by checking your insurer’s provider directory to determine if your preferred physicians, hospitals, and specialists are listed in-network.
Unfortunately, health plan directories can contain errors or outdated listings. Providers listed may have moved, retired, don’t exist, aren’t taking new patients, or have wait lists so long they’re essentially unavailable. To avoid these “ghost networks”, always call the providers and facilities listed in the health plan directory directly to confirm whether they’re in-network and accepting new patients.
Similarly, review the health plan’s drug list (formulary) to ensure your specific prescriptions are covered and to see which cost tier they fall under.
Step 3: Run the “Worst-Case Scenario” Math
Calculate what you would spend in a year if you face a major medical event that reaches the plan’s out-of-pocket maximum by adding that to the annual premiums, as shown above. (This article does not go into marketplace subsidies or an employer paying some or all of your premiums, but you would take these “discounts” into account and write down the actual amount you would be paying for your annual premiums after any discounts.) Comparing these maximum potential costs across a few plans will reveal which coverage option offers the strongest financial protection for your situation.
Free Help Comparing Medicare and Marketplace Plans
The Patient Advocate Foundation has published free, independent Open Enrollment Guides for those choosing Medicare or ACA Marketplace health insurance plans for the coming year.
You can compare ACA Marketplace plans, check your coverage, or find out if you qualify for savings by calling 800-318-2596 or going to HealthCare.gov. On HealthCare.gov, click “Find Local Help” to locate a free health insurance navigator or assister. Learn more about assisters in our article, How to Get Free Help Enrolling in Individual Health Insurance.
For Medicare questions, Medicare.gov, or call 800-633-4227. You can also get free help comparing Medicare costs, coverage, and plans through your State Health Insurance Assistance Program (SHIP) or local Senior Medicare Patrol.
Online Tools for Comparing Health Insurance Plans
When you compare health insurance plans, check out online tools and calculators to help you calculate and apply for subsidies that lower your health insurance costs. Below are a few of them, also listed on our Resources page.
Health Insurance Cost Calculators
- Obamacare (ACA) Subsidy Calculator
- Health Insurance Marketplace Calculator
- Healthcare.gov Income Calculator (to help when applying for individual health insurance and subsidies)
- Health Insurance Plan Comparison Calculator
Other Considerations When Comparing Health Plans: Restrictions and Denial Rates
Health Plan Administrative Burdens
When you compare health insurance plans, consider the administrative burden and network limitations of different plans. For example, most plans have limited networks, require referrals to see specialists, and may have high preauthorization and claim denial rates.
Health Insurance Denial Rates
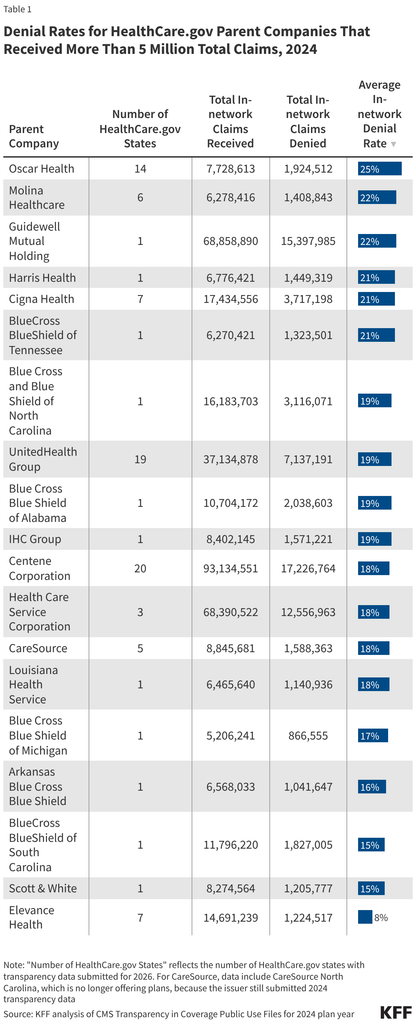
Consider an insurer’s claim denial rate. Although most people don’t appeal insurance claim denials, an insurer’s denial rate could be an indicator of the administrative burden you may face when using your policy.
KFF publishes some claim denial rates for qualified health plans (QHPs) from the federal Marketplace (HealthCare.gov) or a state-based Marketplace that uses HealthCare.gov for eligibility and enrollment. Denial rates vary substantially by insurer. These insurers also sell insurance outside of the ACA Marketplace.
Restrictive Networks and Referral Requirements
When you compare health insurance plans, make sure you understand the plan’s requirements for getting care. For example, going outside a narrow network or failing to get preauthorizations (preapprovals) and referrals can lead to big surprise bills.
Read the health insurance plan’s materials and ask them if you don’t understand any of their basic procedures, such as:
- Do I have to use doctors, hospitals, and urgent care centers in the plan’s network?
- What happens if I choose providers outside the plan’s network?
- Do I need a referral from my PCP before I can see a specialist?
- What are the preauthorization requirements?
Confusing Health Insurance Plan Marketing and Scams
If you don’t get health insurance through an employer, can’t find an affordable plan on the ACA Marketplace (HealthCare.gov), or need insurance outside open enrollment, other options are available. The internet and commercial open market are flooded with a bewildering selection of insurance and health coverage products.
Comparing health insurance plans online through internet searches can be especially frustrating, especially around open enrollment, due to shady health insurance marketing. Junk insurance, deceptive marketing, scams, and rogue insurance agents are after your wallet, credit score, and even your identity. Even a simple internet search often doesn’t give you the result you asked for. Instead, it gives you a list of companies that bid the most money on the keywords you typed. Simply put—buyer beware!
Health Insurance Scam Red Flags
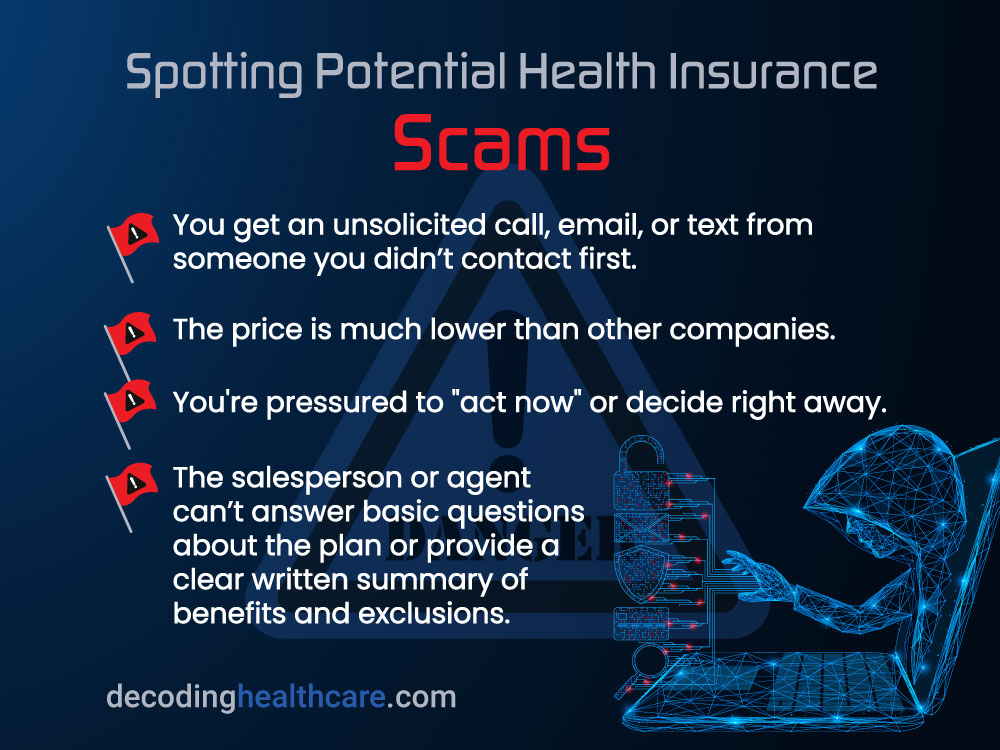
When you compare health plans, there are certain warning signs or red flags to look out for:
- You get an unsolicited call, email, or text from a company or person you didn’t contact first.
- You see a price that is much lower than other companies you’ve checked. This often means the plan has fewer benefits and more exclusions.
- You’re pressured to “act now” or decide right away. There are no limited-time sales or special deals in health insurance.
- The salesperson or agent can’t answer basic questions about the plan or provide a clear written summary of benefits and exclusions.
Decoding Health Care will be publishing more about healthcare scams in the future, so keep following our content!
Health Plans that are not Traditional Health Insurance
When choosing a health insurance plan, it’s important to know if you are buying traditional, comprehensive coverage, like you get from an employer or the ACA Marketplace, or a less comprehensive alternative. Learn more about the differences between traditional health insurance and other coverage—as well as the potential risks—in our main subject articles:
Conclusion
Health insurance is ultimately a tool for managing financial risk. Comparing health plans involves looking beyond the monthly premium and understanding and evaluating deductibles, copays, and out-of-pocket maximums. It also involves taking the time to read the fine print to understand your coverage, exclusions, and limitations. By paying attention to the details and running a few numbers, you can make an informed choice that helps protect both your health and your financial wellness, ensuring your coverage works for you when you need it most!
There are also, unfortunately, a lot of health insurance scams and misleading marketing nowadays, so reading our articles on the basics of health insurance is one way you can improve your health insurance literacy and more easily spot those deals that may be too good to be true.
Frequently Asked Questions: How to Compare Health Plans
Why is choosing a health insurance plan based solely on the lowest monthly premium risky?
Looking at the monthly premium alone reveals only a fraction of your overall healthcare costs. Lower monthly premiums almost always come paired with higher deductibles and higher out-of-pocket expenses. Additionally, low-premium options may contain coverage gaps that result in surprise medical bills for services you assumed were covered.
How does personal cash flow affect the choice between high and low deductibles?
Health insurance selection depends heavily on your available savings and cash flow. Selecting a high-deductible plan without emergency savings is risky because a single unexpected medical bill can cause medical debt. Conversely, if you have predictable medical needs and liquid savings, taking monthly premium savings can be advantageous, especially when using a Health Savings Account (HSA) or Flexible Spending Account (FSA) to pay ongoing care costs.
Why should you check a plan’s provider network and drug formulary when you compare health plans?
Health insurance is only useful if your doctors, hospitals, and medications are covered by your health plan.
What is the recommended 3-step process for evaluating health insurance plans?
- Audit expected healthcare needs: Review your medical history from the prior year and project future needs—such as routine check-ups, ongoing prescriptions, and planned procedures—to estimate if you will likely exceed the deductible.
- Check provider networks and drug formularies: Check the health plan’s provider directory and verify in-network status by contacting the providers directly. Also, review the plan’s drug formulary to check medication coverage and cost tiers.
- Run worst-case scenario math: Out-of-pocket maximum + annual premiums.
Why should you consider an insurer’s claim denial rate and administrative rules?
An insurer’s claim denial rate indicates the potential administrative friction you may experience after enrolling. Furthermore, failing to adhere to plan administrative rules—such as primary care referrals, preauthorizations, or staying within strict networks—can result in substantial out-of-pocket surprise bills and/or medical debt.
What red flags indicate potential health insurance scams or junk insurance?
Shopping for coverage outside employer plans or official ACA Marketplaces exposes consumers to deceptive marketing and non-traditional junk insurance. Major red flags include:
- unsolicited phone calls, emails, or text messages
- prices significantly lower than competing plans
- high-pressure tactics demanding immediate decisions
- agents who cannot clearly explain in writing plan benefits, restrictions, or exclusions
Article by Lauren R. Jahnke, MPAff, Author of Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money, and Julie Gunstanson, Certified Medical Billing Advocate.
Last update: 10-3-2026
Disclosures: This article provides general educational information, not legal or financial advice. For guidance specific to your situation, consult a licensed broker, agent, or insurance navigator in your area. Decoding Health Care provides independent and educational information and does not endorse any specific insurance plans or other health coverage products. AI tools were used to assist with researching this article; however, human subject-matter experts always extensively revise, fact-check, edit, and approve our content.