
Decoding Alternative Health Plans
Millions have been priced out of comprehensive health insurance by skyrocketing premiums, with ACA enrollment dropping 20% since 2025. As a result, many consumers are turning to alternative health plans, such as healthcare cost-sharing plans or ministries, short-term health insurance, limited health plans, discount plans, and “packaged medical insurance.” Alternative health plans can be significantly less expensive than traditional health insurance without open-enrollment periods, but it’s important to understand the risks.
Table of Contents
- How Alternative Health Plans are Different from Traditional Insurance
- Healthcare Cost-Sharing Ministries and Similar Plans
- Membership Discount Plans
- Non-Comprehensive Health Insurance
- Customizing Your Own Coverage
- Frequently Asked Questions (FAQs)
- Key Points
- Glossary
How Alternative Health Plans are Different from Insurance
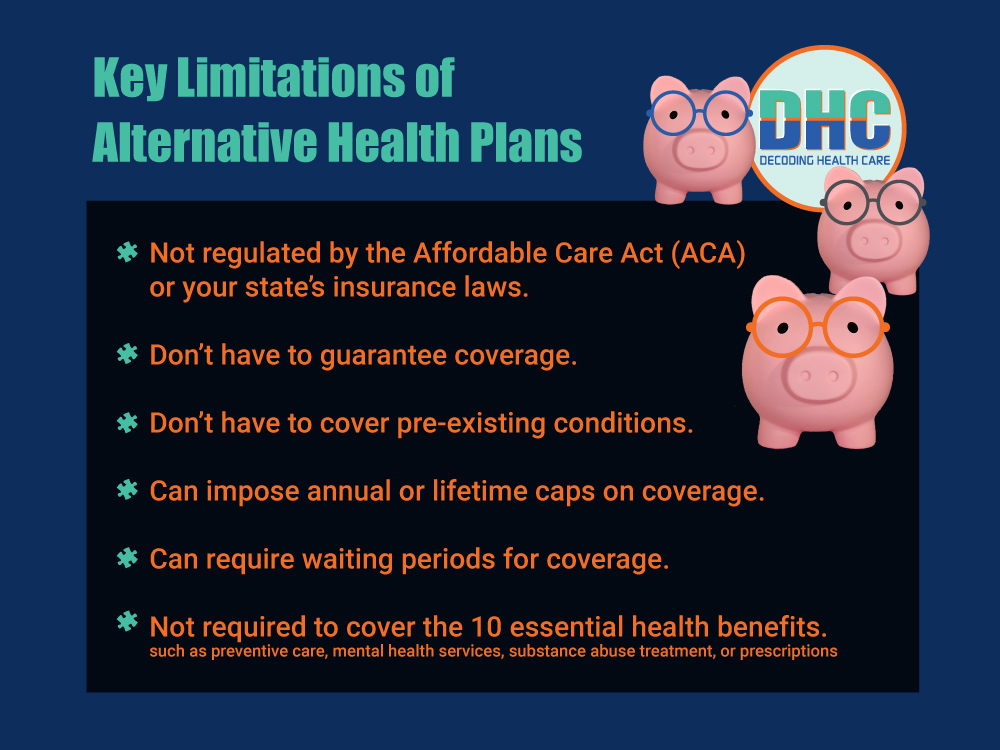
Alternative health plans are not traditional insurance, aren’t regulated like insurance, and don’t offer the same consumer rights and protections. This lack of financial protection can leave you exposed to high medical bills — even medical debt.
Limitations of Alternative Health Plans
Alternative health plans:
- Are not insurance and not regulated by state insurance laws
- Are not regulated by the Affordable Care Act (ACA)
- Don’t have to guarantee coverage
- Don’t have to cover pre-existing conditions
- Can impose annual or lifetime caps on coverage
- Can require waiting periods for coverage
- Aren’t required to cover the ten essential health benefits, such as preventive care, mental health services, substance abuse treatment, or prescriptions
Lack of awareness of the risks and limitations, as well as confusing marketing, has earned these alternative health plans the nickname “junk health insurance” by consumer advocates. Although not an official category, it describes health plans that look like insurance but may leave you owing large medical bills when you actually need care. Critics warn that problems arise when people use alternative health plans as primary insurance and don’t realize the coverage is inadequate until they need it most.
Critics also point to marketing efforts that make these plans seem comprehensive and bury their limitations in the fine print. With the enhanced subsidies for ACA marketplace insurance expiring, alternative health plans have been increasing their marketing efforts. Even more confusing, individuals reported googling “Obamacare” in 2025 and being steered towards these products when trying to shop for ACA Marketplace insurance.
Proponents argue that restricting alternatives to pricey marketplace plans will result in more uninsured people. They say that for individuals without adequate health insurance, these health plans and other alternative healthcare options can be a lifeline.
Healthcare Cost-Sharing Ministries and Similar Plans
Healthcare cost-sharing ministries are also known as medical sharing networks, healthcare sharing plans, or similar names. These are a form of health coverage in which members with common religious or ethical beliefs share medical costs. Monthly payments are often significantly lower than traditional insurance premiums, and individuals can sign up anytime with no specified open enrollment periods. These plans rarely have provider networks or negotiated discounts with providers, allowing members to visit any doctor or hospital but often requiring them to negotiate their own “cash” discounts.
Because these plans are not insurance, they have much less government regulation and oversight. Cost-sharing networks do not maintain financial reserves and aren’t legally obligated to pay member claims. They may only be able to reimburse a percentage of medical costs if there is a funding shortfall in a given month. Enrollees in religious cost-sharing ministries must sign a statement of faith and a pledge for healthy living, and the plans may not cover treatment against their beliefs, such as birth control. They also don’t cover people who smoke.
Many people have positive experiences with cost-sharing ministries, but there have also been issues reported and lawsuits in various states. Some consumers don’t understand that these plans are different from health insurance and have felt misled.
More cost-sharing plans that are not religion-based are also starting to appear, such as CrowdHealth and Zion HealthShare. These are growing in popularity since they are cheaper than traditional insurance, but some states are warning consumers about the drawbacks of these plans. Because these alternative health plans offer no consumer protections, you should study the specifics before buying.
Discount Plans
Healthcare discount plans, such as AmeriPlan, are also popular options. These are often subscription arrangements where you usually pay a fee to access a network of providers who have agreed to lower their rates for members. Unlike insurance, these plans don’t pay the doctor for you; they simply act as a “membership club” that grants you access to pre-negotiated cash prices. They can be especially helpful for services that insurance often skips, like dental or vision care. Just be sure to verify that the plan has enough participating providers in your area before signing up, and always keep an eye out for potential scams.
Non-Comprehensive Health Insurance
Depending on your specific needs, non-comprehensive insurance can be an affordable alternative to traditional health insurance. Although sold by many of the same companies that also sell plans on the federal and state marketplaces, it’s not the same. These plans don’t have to comply with ACA mandates, making them much cheaper than standard insurance. As a result, non-comprehensive insurance offers less financial protection and can expose you to significant out-of-pocket costs.
However, if you understand all the plan details, and depending on your needs and budget, you may find non-comprehensive insurance a viable alternative to traditional health insurance.
Short-Term Insurance
Short-term health insurance is a common choice for those in transition with a gap in insurance, offering temporary coverage for anywhere from 4 to 36 months, depending on the state and the insurer. Like other non-comprehensive insurance options, it can come with significant trade-offs: they can deny coverage for pre-existing conditions and frequently exclude essential services like maternity care or prescription drugs. Also, several states prohibit short-term plans, and several states have none available in the state.
Limited Health Plans
For more targeted protection, specialized policies allow you to pay specifically for the risks you are most concerned about. For instance, accident insurance provides a cash payout for specific injuries, while critical illness plans offer a lump sum if you are diagnosed with a major condition like cancer or stroke. Other options include hospital indemnity plans, which pay a set amount for each day you are hospitalized, and standalone dental or vision coverage. These plans are often inexpensive, but it is important to remember they are not “major medical” insurance and generally won’t cover routine care or chronic illnesses.
Customizing Your Own Coverage
Some consumers now use a strategy called “packaged medical insurance,” where they bundle several of these limited plans together (and maybe discount cards or other methods too) to create a customized hodge-podge of coverage. This can significantly lower monthly premiums compared to a full-scale policy. The risk, however, is that you may still face high out-of-pocket costs for services not included in your specific “package.” If you choose this route, always read the fine print to understand the limitations.
Frequently Asked Questions (FAQs)
What are alternative health plans?
Alternative health plans are limited or non-comprehensive health coverage plans. They are not insurance, and include healthcare cost-sharing plans or ministries, short-term health insurance, limited health plans, discount plans, and “packaged medical insurance.”
Why do some consumers choose non-insurance health plans?
Many people are turning to alternative health plans because they don’t have pre-defined open enrollment periods and they’re significantly less expensive than traditional insurance. Skyrocketing premiums have priced millions of consumers out of traditional insurance, contributing to a 20% drop in ACA enrollment since 2025.
How do alternative health plans differ from traditional health insurance?
Alternative health plans are not traditional insurance. They are not regulated by the states as insurance or governed by federal insurance laws, such as the Affordable Care Act (ACA). Because they lack government oversight and regulation, they don’t offer the same consumer rights, legal protections, or financial safety nets, which can expose you to severe financial risks and medical debt.
What are the key limitations of alternative health plans?
These plans are not required to cover essential health benefits, which include vital services like preventive care, prescriptions, mental health, and substance abuse treatment. Additionally, they don’t have to guarantee coverage, can exclude pre-existing conditions, and are free to require waiting periods or impose lifetime and annual caps on your coverage.
Why are alternative health plans sometimes referred to as “junk insurance”?
Critics warn that confusing marketing efforts make these plans look like comprehensive insurance. These tactics vary from burying the limitations in fine print to steering individuals searching online for “Obamacare” towards these products. This has earned them the nickname “junk health insurance” because people often don’t realize their coverage is inadequate until they need care and are left owing large medical bills.
How can you avoid buying “junk insurance”?
Always read the fine print, including coverage, network, and exclusion details. Understand what you are signing up for.
Key Points
- Alternative health plans can be significantly less expensive than traditional health insurance without open enrollment restrictions, but it’s important to understand the risks and trade-offs.
- Alternative health plans include healthcare cost-sharing ministries, non-comprehensive health insurance, and medical discount programs.
- Alternative health plans are not traditional health insurance and don’t offer the same legal protections and comprehensive coverage.
- Confusing marketing by some alternative health plans makes them look like traditional health insurance.
- Always read the fine print and understand what you are signing up for.
The main source for this article is chapters 8-10 of our book, Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money, by Lauren R. Jahnke. This is a comprehensive consumer guide to understanding health insurance and health coverage options in the U.S. It includes many practical tips to help you decipher the options and save money — with or without insurance.
Article by Julie Gunstanson, Certified Medical Billing Advocate, and Lauren R. Jahnke, MPAff, author of Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money.
Last article update: 10-2-2026
Disclaimers and disclosures: This article provides general information about healthcare options. For guidance specific to your situation, consult insurance brokers and navigators, patient advocates, social workers, or other experts as appropriate in your area. Decoding Health Care provides independent and educational information and does not endorse any specific insurance plans or health coverage products. AI tools were used to assist with researching this article; however, human subject-matter experts always extensively revise, fact-check, edit, and approve our content. Affiliate disclosure: GoodRX is an affiliate link that supports our content.
Do You Have a Medical Bill You Can’t Afford or Medical Debt in Collections?
Before you pay that big medical bill, read this!
Get our Free Medical Debt Quick Start Guide and learn the first steps to take before sending a dollar to a medical provider or collection agency.
By submitting this form, you agree to receive educational emails from Decoding Health Care, our free guide, and our free monthly DHC Insider, an educational newsletter focused on protecting your finances from high healthcare costs and medical debt—with or without insurance. You may unsubscribe at any time. Click here for our Privacy Policy