8 Costly Health Insurance Mistakes That Lead to Surprise Medical Bills and High Out-of-Pocket Costs
Common mistakes made when choosing health insurance can lead to surprise medical bills and high out-of-pocket costs when it’s time to use your coverage. Here is our list of 8 costly health insurance mistakes that can leave you financially exposed to unpaid medical bills, and even medical debt!
You may find it helpful to review Health Insurance Terms: Costs and Coverage Explained for help understanding terms related to benefits, coverage, exclusions, networks, formularies, deductibles, copays, coinsurance, and out-of-pocket costs.
Table of Contents
Health Insurance Scams
Confusing Health Insurance with Access
Automatic Re-enrollment
Junk Insurance
Choosing Health Insurance Solely by Premium Price
Health Plan Documents and Fine Print
Open Enrollment Deadlines
Medical History and Pre-existing Conditions
Frequently Asked Questions (FAQs)
What’s the Most Costly Health Insurance Mistake?
1. Falling for a Health Insurance Scam
We’ll start with the most costly health insurance mistake people make—falling for a health insurance scam. This type of healthcare fraud is a serious problem—especially during Open Enrollment. It often starts with an online search for “cheap health insurance,” “affordable healthcare,” or “Obamacare plans” and accidentally landing on a fake website. Sometimes it starts with an unsolicited call, text, email, or social media message offering cheap insurance that covers everything with little out-of-pocket costs.
The consequences of health insurance scams can be more severe than the other items on our list because they can also expose you to medical identity theft.
Read more about health insurance scams in our next article.
Health Insurance Mistakes that Lead to Higher Out-of-Pocket Costs
Now that we’ve covered the most frightening and costly health insurance mistake on our list, the following leave you financially exposed to high out-of-pocket costs for medical care and prescriptions you thought were covered. It’s often only after receiving a surprise bill, a shock at the pharmacy counter, or a denial letter that people realize they’ve made a costly health insurance mistake.
2. Confusing Health Insurance with Access to Health Care
Why would anyone choose a health plan they can’t use? Yet, you could make that costly health insurance mistake if you don’t do your homework. Having health insurance isn’t the same as having access to medical or healthcare services. When comparing health plans, make sure your providers and medications are covered in-network to ensure access to health care and lower out-of-pocket costs.
Check and Verify the Provider Network
Failing to check if your nearby primary care doctors, specialists, therapists, clinics, hospitals, and pharmacies participate in a plan’s network can lead to full-price or out-of-network charges.
A health insurer’s provider directory could contain ghost networks. This refers to inaccurate listings of providers or clinics as available and in-network when they are not. Incorrect provider information could include the wrong specialty, practice location, or contact details. Ghost networks may list providers who have moved, retired, don’t exist, are out-of-network, or aren’t taking new patients. Sometimes the listed providers don’t have appointments available for many months, making them essentially unavailable.
Protect yourself from ghost networks in four steps.
- Check the insurer’s Provider Directory for providers listed as in-network with the health plan.
- Contact the providers directly to verify in-network status with both the insurer and the individual health plan.
- Verify the in-network status of both your chosen doctors and the facilities where they work. One may be in-network while the other isn’t.
- If the provider is new to you, ask if they are taking new patients and how long it takes to get an appointment.
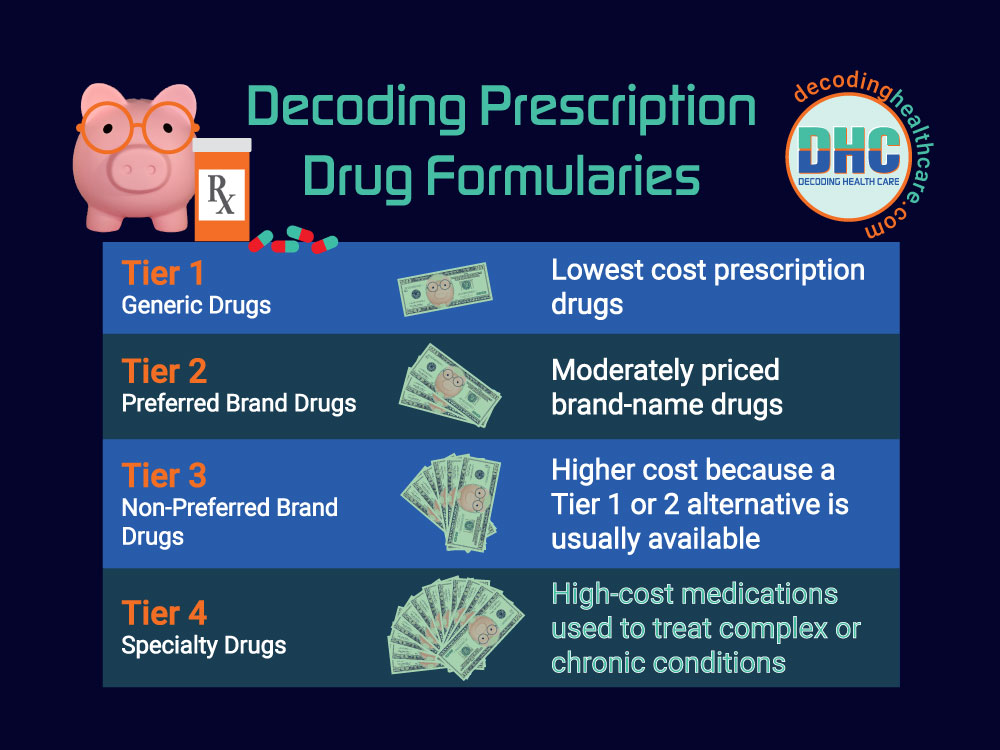
Don’t Overlook the Prescription Drug Formularies
Assuming all plans cover your medications the same way is another costly health insurance mistake. Plans often change and update their formularies. Formularies use different price tiers, and your drug may require prior authorization, carry strict limits, have higher out-of-pocket costs, or not be covered at all.
3. Automatically Re-Enrolling In Last Year’s Health Plan Without Review
It’s a common health insurance mistake to assume last year’s health plan will be the same next year. Never automatically re-enroll in last year’s plan without reviewing the policy details, networks, and prescription formularies. The health plan’s rules and costs also may have changed. Not reviewing the policy changes for the next plan year can lead to unexpected out-of-pocket costs after your plan goes into effect.
4. Accidentally Buying Junk Insurance
Don’t confuse comprehensive insurance with alternative health insurance, alternative health plans, and other coverage products. Many are marketed as “health insurance,” “health plans,” and “Obamacare plans.” If you can’t tell if you’re looking at comprehensive health insurance or something else, you may be looking at junk insurance.
“Junk insurance” is a nickname consumer advocates use to describe low-cost, low-quality alternative health insurance, discount plans, and other coverage products marketed to look like comprehensive insurance when they’re not.
These alternatives are not the same as traditional insurance, like you get from an employer, the ACA Marketplace, or a government-sponsored program. They aren’t regulated like health insurance and don’t offer the same level of coverage and benefits. When people sign up for these plans without knowing their limitations, they can be left responsible for medical bills they thought were covered.
However, these options may be a good fit for people who want more affordable, less comprehensive coverage and who understand the risks. To protect yourself, always read the fine print. We’ll cover that topic in #6 on our list below.
If you are considering these options, read our article, Decoding Alternative Health Insurance and Alternative Health Plans.
5. Choosing Health Insurance Solely by Premium Price
Picking the plan with the lowest monthly premium often means you will face much higher deductibles, copays, and out-of-pocket costs when you actually need care. Misunderstanding the total cost of health insurance is a common health insurance mistake that can lead to big medical bills, even medical debt. Beyond the monthly premium, you must calculate the combination of deductibles, coinsurance, copays, and the annual out-of-pocket maximum.
This topic is covered in greater detail in our previous article, How to Compare Health Insurance Plans.
6. Failing to Understand the Health Plan Documents and Fine Print
Never feel pressured to decide on the spot or “act now”. That could be a sign of a health insurance scam. Always take the time to review your plan’s details, rules, and documents. Pay particular attention to a health plan’s coverage, exclusions, and limitations. Follow the steps in #2 on our list above, ensuring the plan gives you access to providers in your area and covers your prescriptions.
Skipping the fine print regarding service exclusions, mental health coverage, maternity care, or limits on therapies like physical or occupational care could leave you responsible for high out-of-pocket costs for unpaid medical bills you thought were covered.
On insurer websites, look for “coverage details” or “what’s covered” or similar phrases.
Essential Documents to Prevent Costly Health Insurance Mistakes
Common coverage documents that can be found on insurer websites or mailed in paper copies include:
- Summary of Benefits and Coverage (SBC) for standard ACA-compliant private or employer-sponsored health plans
- Summary Plan Description (SPD) for other employer-sponsored health plans
- Evidence of Coverage (EOC), often used in HMOs or Medicare plans
- Certificate of Coverage – a summary document of specific medical benefits, plan operations, provider networks, and cost-sharing rules
Note: If a salesperson or agent can’t provide written documentation and explain clearly the plan rules, coverage, costs, limitations, and exclusions, stop! They may be a scammer or selling “junk insurance.”
7. Missing Open Enrollment Deadlines
Forgetting deadlines, or failing to make the initial payment required to activate your coverage, is a costly health insurance mistake that will leave you uninsured. Enrollment dates and deadlines vary according to where you get your insurance.
If you get your insurance from your job, your open enrollment period is determined by your employer.
Marketplace Open Enrollment Dates
In most states, if you buy health insurance through the ACA Marketplace (HealthCare.gov), Open Enrollment runs from November 1 through January 15.
- November 1: Open Enrollment starts. You can enroll in, renew, or change your health plan.
- December 15: Last day to enroll or change plans for coverage starting January 1.
- January 1: Coverage begins for people who enrolled and paid their first premium by December 15.
- January 15: Open Enrollment ends. After this date, you cannot change or buy a plan unless you qualify for a Special Enrollment Period (SEP).
- February 1: Coverage begins for people who enroll between December 16 and January 15.
If you get Medicare, you need to be aware of a different set of enrollment dates.
Key Medicare Enrollment Dates & Periods
- Initial Enrollment Period (IEP): This is the 7-month window surrounding your 65th birthday (3 months before, the month of, and 3 months after) or your eligibility month for Medicare.
- January 1 – March 31: General Enrollment Period (GEP)
Sign up for Medicare Part A and/or Part B if you missed your Initial Enrollment Period (late enrollment penalties may apply). - October 15 – December 7: Annual Open Enrollment Period (AEP / Fall Open Enrollment). You can join, drop, or switch to a Medicare Advantage Plan (Part C) with or without drug coverage; add or drop a Medicare Part D prescription drug plan; or switch from Original Medicare to a Medicare Advantage Plan (or vice versa).
- January 1 – March 31: Medicare Advantage Open Enrollment Period (MAOEP)
If you are already enrolled in a Medicare Advantage plan, you can switch to a different Medicare Advantage plan or drop your Medicare Advantage plan to return to Original Medicare (and add a standalone Part D plan) once during this period.
You can only change or sign up for comprehensive health insurance outside standard windows if you qualify for a Special Enrollment Period (SEP). Moving, losing employer-sponsored health coverage, having or adopting a baby, or losing Medicaid are examples of qualifying life events that could make you eligible for a SEP.
Note: Alternative health insurance and health plans that aren’t traditional insurance are typically available year-round. Additionally, you can enroll in Medicaid or the Children’s Health Insurance Program (CHIP) any time, if you qualify.
8. Concealing or Forgetting Medical History or Pre-existing Conditions
When purchasing alternative health insurance and alternative health plans, hiding pre-existing conditions, not accounting for waiting periods, or not understanding the plan’s limitations can result in denied claims or delayed coverage.
Note: ACA Marketplace Plans and many federally regulated health insurance plans are prohibited from considering pre-existing conditions or imposing waiting periods.
Frequently Asked Questions (FAQs)
What’s considered the most costly health insurance mistake a consumer can make?
Falling for a health insurance scam is identified as the most costly mistake a consumer can make. In addition to financial losses, this type of healthcare fraud can expose you to medical identity theft.
What’s a ghost network and how can you avoid them?
A ghost network occurs when an insurer’s directory lists providers or clinics as active and in-network when they have actually moved, retired, ceased participating in the plan, don’t exist, stopped accepting new patients, or have appointment backlogs stretching several months. Patients can protect themselves by checking the directory, contacting providers directly to verify their network status under that specific plan, confirming that both the doctor and the facility where care is delivered are in-network, and asking how long it takes to schedule a visit.
What’s “junk insurance,” and how does it differ from traditional coverage?
Junk insurance refers to lower-cost, lower-quality alternative health plans and other discount and coverage products marketed to look like traditional insurance. Unlike traditional employer-sponsored or ACA Marketplace plans, these products are not regulated like standard health insurance and don’t offer comprehensive benefits or standard consumer protections. If you are considering discount plans, alternative health insurance, or similar coverage products, make sure you understand what you’re signing up for.
What happens if I miss enrollment deadlines, like Open Enrollment?
Missing these windows leaves consumers uninsured unless they qualify for a Special Enrollment Period (SEP) through life events like moving, losing coverage, or having a child.
Why does having health insurance not guarantee access to medical care?
Holding an insurance policy is worthless if your doctors, specialists, hospitals, therapies, and prescription drugs aren’t available and covered in-network by the plan. Always check the written fine print of your health plan. Verify the provider network and check for your medications on the prescription drug formulary. Make sure you understand the costs, coverage, benefits, rules, limitations, and exclusions so you’ll avoid costly health insurance mistakes.
Article by Julie Gunstanson, Certified Medical Billing Advocate, and Lauren R. Jahnke, MPAff, author of Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money.
Disclosures: AI tools were used to assist in researching this article; however, human subject matter experts always extensively revise, fact-check, edit, and approve our content. This article provides general health insurance literacy information. For guidance specific to your situation, consult a licensed broker or insurance agent, health insurance navigator, or assister in your area. Decoding Health Care provides independent and educational information and does not endorse any specific insurance plans or other health coverage products.