Health Insurance Terms: Costs and Coverage Explained
Protecting your finances starts with understanding basic health insurance terms, especially related to costs and coverage. Our main topic article, Decoding Health Insurance Literacy, explains how health insurance literacy is one of the most effective ways to protect your physical and financial health. Understanding basic health insurance terms is foundational to choosing a health plan that fits your needs and budget, as well as estimating and controlling out-of-pocket costs. Before comparing, buying, or using health insurance, it can be helpful to review the basic vocabulary of health insurance terms.
The vocabulary of health insurance terms is quite lengthy, so this article focuses on health insurance costs and coverage terms.
Table of Contents
Health Insurance Cost Terms
Health Insurance Coverage Terms
Frequently Asked Questions: Health Insurance Costs and Coverage
Glossary
Understanding Health Insurance Cost Terms
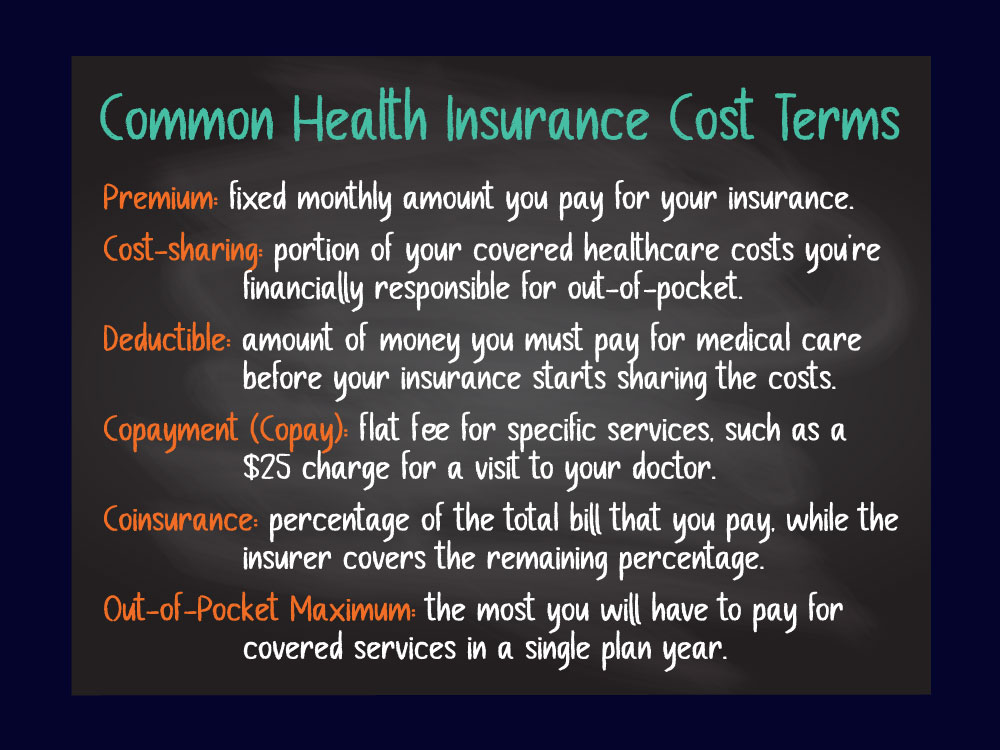
While insurance paperwork can be dense, most plans rely on a standard set of financial health insurance terms used to define how covered healthcare costs are split between you and your health insurance plan.
Premium
Your premium is the fixed amount you pay for your insurance every month, whether you visit a doctor or not. Think of it like a subscription fee that keeps your coverage active.
Cost-Sharing and Out-of-Pocket Costs
Cost-sharing is the portion of your healthcare costs you must pay out-of-pocket while your insurance plan covers the remaining balance. This is the amount you are financially responsible for and includes copays, coinsurance, and deductibles.
Under private health insurance and Medicare, “out-of-pocket costs” generally only refer to cost-sharing incurred when a person has medical claims (even though premiums are also paid out-of-pocket).
Deductible
This is the amount of money you must pay out-of-pocket for medical care before your insurance starts sharing the costs. For example, if you have a $2,000 deductible, you generally pay the first $2,000 of your medical bills before the insurance company begins paying its share.
Note: If you have insurance that’s compliant with Affordable Care Act (ACA) mandates, many preventive care services, like annual wellness exams, are usually covered 100% even if you haven’t met your deductible yet.
Copayment (or “Copay”) and Coinsurance
Once you’ve met your deductible, you still share costs with your insurer under most plans using one of these two methods. A copay is a flat fee for specific services, such as a $25 charge for a primary care visit. Coinsurance is a percentage of the total bill—such as 20%—that you pay, while the insurer covers the remaining 80%.
Out-of-Pocket Maximum
Out-of-Pocket Maximum is your financial safety net. It represents the most you will have to pay for covered services in a single plan year. Once your cumulative spending on deductibles, copays, and coinsurance hits this ceiling, your insurance pays 100% of all covered medical costs for the rest of the year. For some plans (especially high-deductible plans), the out-of-pocket maximum may be the same amount as your deductible, but it’s usually higher.
Note: Alternative health plans, such as health care sharing ministries, are exempt from the Affordable Care Act (ACA) rules that cap your yearly out-of-pocket spending.
Health Insurance Coverage Terms
In addition to the common financial terms above, health insurance coverage terms are also important to know.
Covered Benefits and Plan Exclusions
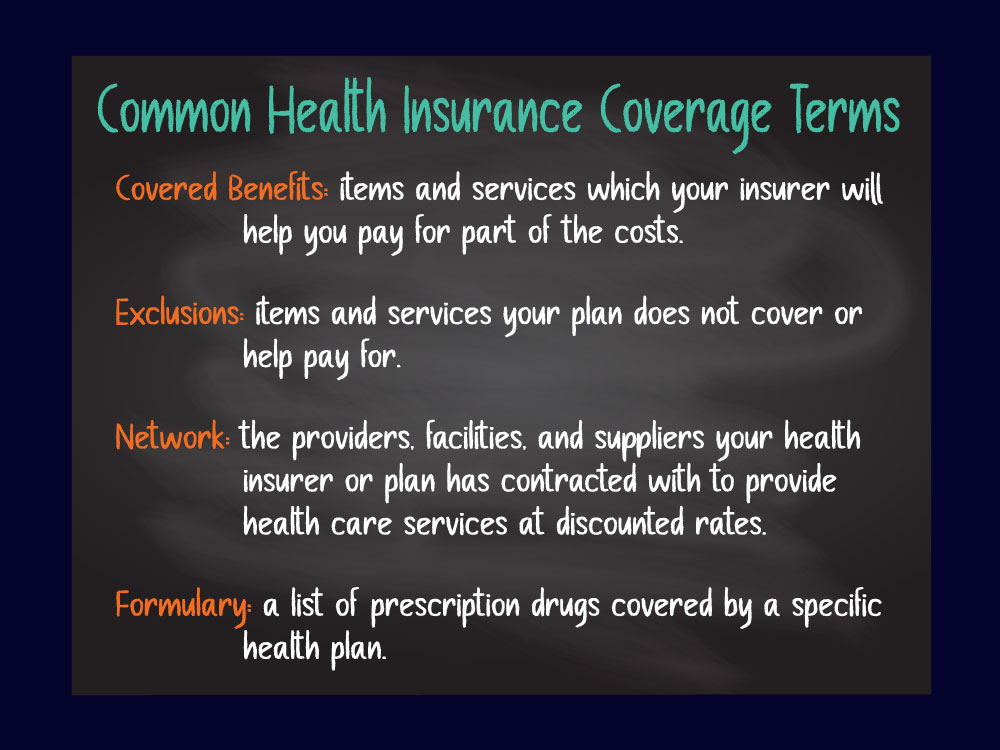
Health insurance doesn’t cover all of your medical expenses. So, you will need to pay attention to your plan’s coverage documents. Look for a Summary of Benefits and Coverage and other documents that define which items and services are covered benefits under a health insurance plan. These are services and items your insurer will help you pay for, depending on your plan.
Note: ACA Marketplace plans, as well as all new individual and small-group health insurance policies since 2014, must cover a list of essential health benefits.
Health plans also list excluded services (non-covered benefits), which are items and services your plan does not cover or pay for. Common exclusions include travel vaccines, massage therapy, alternative therapies, cosmetic procedures, experimental treatments, gym memberships, treatments or services your plan considers not medically necessary, and more.
Note: Alternative health plans, such as health care sharing ministries, are not regulated by ACA mandates. They can have many exclusions that Marketplace plans must cover, such as treatment for pre-existing conditions, routine preventive care, prescription drugs, reproductive care, and mental health and substance abuse treatments.
Network
A network is the providers, facilities, and suppliers your health insurer or plan has contracted with to provide health care services at discounted rates. It includes providers such as primary care doctors, specialists, therapists, and other licensed healthcare providers. It also includes hospitals, clinics, labs, pharmacies, imaging centers, etc. By using in-network providers, you pay less out-of-pocket. Your health insurance plan may pay nothing to very little for planned, out-of-network health care.
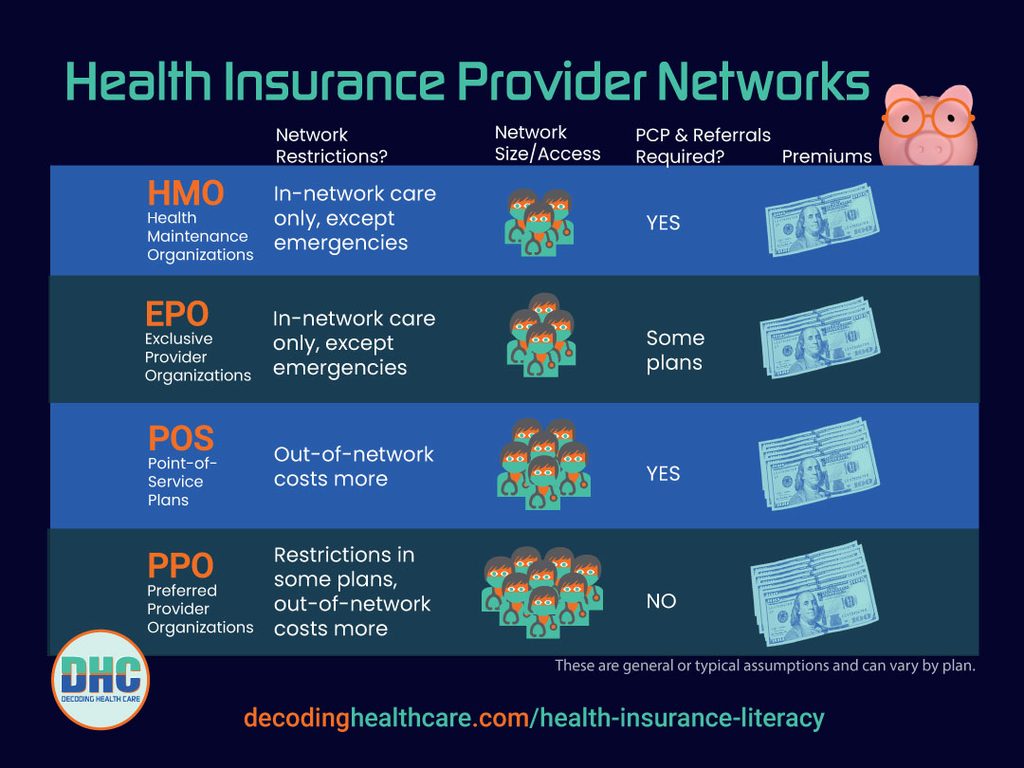
Note: Networks change, so always confirm with your health plan and directly with the providers listed whether they are in-network. When you receive care, always make sure that all doctors and facilities involved in your health care are in-network. The hospital may be in-network while one of your doctors are not.
Formulary
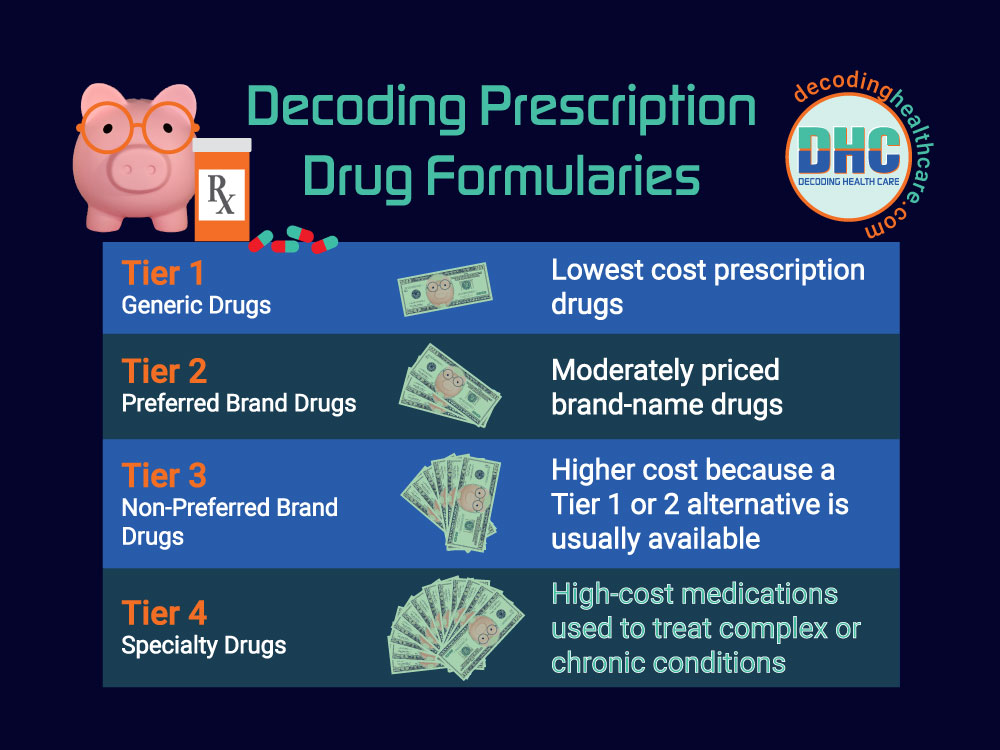
A formulary is a list of prescription drugs covered by a specific health plan. You can use your insurer’s online portal to verify if your exact prescription is covered and what tier it falls under. Formularies are divided into tiers or categories, which determine your out-of-pocket costs.
- Tier 1 (Generic Drugs): Prescriptions with the lowest copay or coinsurance. (Some formularies have 2 generic drug tiers.)
- Tier 2 (Preferred Brand Drugs): Moderately priced brand-name drugs that the insurer prefers.
- Tier 3 (Non-Preferred Brand Drugs): Higher-cost drugs because a preferred or generic alternative is usually available.
- Tier 4 (Specialty Drugs): High-cost medications used to treat complex or chronic conditions.
Note: Insurance companies update their formularies periodically throughout the year as new drugs are released or prices change.
More Health Insurance Terms
Bookmark our Health Insurance Glossary as a reference for more health insurance terms you need to know as you navigate health care, coverage, and medical billing. Additionally, we have a Resource Page packed with third-party tools, websites, and apps you’ll find helpful for managing your healthcare costs—with or without insurance. These pages will evolve and grow as we add content to our website. If you know of any resources that should be added to our list and shared with our audience, please reach out to us at info@decodinghealthcare.com.
Learn about Health Insurance and the Alternatives
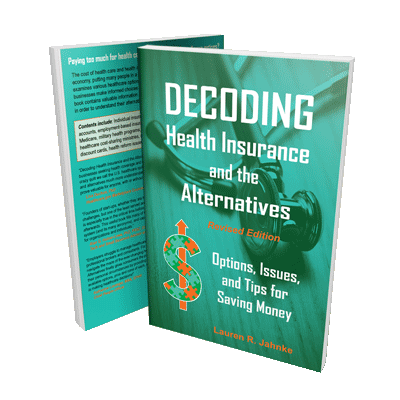
Our book, Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money, by Lauren R. Jahnke, MPAff, is a comprehensive, non-partisan consumer guide to understanding the current U.S. system for health insurance and getting health care. It includes many practical tips to help you save money, whether you have insurance or not.
Additionally, you can subscribe to our free monthly newsletter, the DHC Insider. You’ll stay up to date on recent national issues and legislation affecting healthcare affordability. You’ll also get the latest tips, resources, tools, and hacks to spend less on health care, with or without insurance.
Conclusion
Health insurance literacy begins with an understanding of the basic vocabulary of health insurance terms. With it, you’ll make better, more informed choices that help protect both your health and financial wellness.
Frequently Asked Questions: Understanding Health Insurance Cost and Coverage Terms
Why is understanding health insurance terms important?
Understanding essential health insurance vocabulary, especially terms specific to costs and coverage, empowers individuals to choose a health plan that aligns with their budget and healthcare needs while better estimating out-of-pocket expenses.
Does health insurance pay for all your health care?
No. Health insurance pays only part of your healthcare costs—depending on your health plan’s benefits and coverage, exclusions, cost-sharing, and details in the fine print.
What is a health insurance premium?
A premium is a recurring fixed fee usually paid every month to keep health coverage active, functioning like a subscription regardless of whether medical services are used.
What are cost-sharing and out-of-pocket costs?
Cost-sharing represents the portion of covered healthcare expenses you pay out-of-pocket —including deductibles, copays, and coinsurance—while the health plan covers the remaining costs.
How does a deductible work?
A deductible is the specific dollar amount an individual must pay out-of-pocket for healthcare services before the insurance plan begins paying its share.
What is the difference between a copay and coinsurance?
A copayment (copay) is a fixed flat fee paid for a specific service, such as a set $25 fee for a doctor visit. Coinsurance is a percentage of the total bill—such as 20%—that you pay after meeting your deductible.
What is an out-of-pocket maximum?
The out-of-pocket maximum is the most you should have to pay for covered care in a single plan year. Once spending on deductibles, copays, and coinsurance reaches this limit, the insurer covers 100% of remaining covered medical costs for the rest of the year.
What are covered benefits versus plan exclusions?
Covered benefits are the medical services and items an insurer helps pay for according to the plan’s Summary of Benefits and Coverage. Exclusions are services the plan does not cover, such as cosmetic procedures, travel vaccines, gym memberships, or treatments your insurer considers not medically necessary.
How does a provider network function?
A network consists of doctors, facilities, and pharmacies contracted with an insurer to deliver care to individuals covered under its health plan at discounted rates.
How do provider networks impact out-of-pocket expenses?
Provider networks directly determine how much you pay out-of-pocket for covered medical services. Using in-network providers keeps out-of-pocket costs lower, whereas health plans may pay little or nothing for out-of-network care.
What is a prescription drug formulary and how do its tiers work?
A formulary is an insurer’s list of covered prescription drugs divided into pricing tiers. Tier 1 includes generic drugs with the lowest copays, Tier 2 includes preferred brand-name drugs, Tier 3 includes non-preferred brand-name drugs, and Tier 4 covers specialty drugs for complex or chronic conditions.
Article by Lauren R. Jahnke, MPAff, author of Decoding Health Insurance and the Alternatives: Options, Issues, and Tips for Saving Money, and Julie Gunstanson, Certified Medical Billing Advocate.
Article Last Updated: 10-5-2026
Disclaimers and disclosures: This article provides general information about healthcare options. For guidance specific to your situation, consult insurance brokers, financial counselors, billing advocates, legal assistance, or other experts in your area, as appropriate. Decoding Health Care provides independent and educational information and does not endorse any specific insurance plans or health coverage products. AI tools were used to assist with researching this article; however, human subject-matter experts always extensively revise, fact-check, edit, and approve our content. Affiliate disclosure: GoodRX is an affiliate link that supports our content.
Do You Have a Medical Bill You Can’t Afford or Medical Debt in Collections?
Before you pay that big medical bill, read this!
Get our Free Medical Debt Quick Start Guide and learn the first steps to take before sending a dollar to a medical provider or collection agency.
By submitting this form, you agree to receive educational emails from Decoding Health Care, our free guide, and our free monthly DHC Insider, an educational newsletter focused on protecting your finances from high healthcare costs and medical debt—with or without insurance. You may unsubscribe at any time. Click here for our Privacy Policy